50/30/20 Budget Breakdown for a $33k Salary: The Complete Framework
A $33,000 salary doesn’t get much love in budgeting articles obsessed with six-figure incomes and lattes debates. But run the 50/30/20 budget breakdown on a $33k salary and you’ll find a framework that actually works — because the ratios force smart decisions when every dollar has a job to do. Here’s exactly what your numbers look like, category by category, plus the adjustments most people earning $33k actually need to make to survive and save.
What a $33k Salary Actually Pays You Each Month
Before you can apply the 50/30/20 budget breakdown to $33k, you need your real take-home pay — not the number on your offer letter. Gross annual pay of $33,000 breaks down to $2,750 per month or $1,269.23 every two weeks if you’re paid biweekly. But that’s not what lands in your checking account.
Gross vs. Net: The Number That Actually Matters
Assuming a single filer with no dependents, the standard deduction, and average withholding, here’s a realistic breakdown:
- Federal income tax: roughly $1,800–$2,100/year
- FICA (Social Security + Medicare): 7.65% = about $2,525/year
- State income tax: $0 in Texas, Florida, or Washington; roughly $600–$1,200/year in states with moderate income tax
Net out to roughly $2,275–$2,325 per month depending on your state. For clean math throughout this guide, we’ll use $2,300/month net income — a realistic, commonly cited take-home figure for a $33k salary.
Pay Frequency Matters More Than You Think
If you’re paid biweekly, you’ll get two ‘extra’ paychecks a year (months with three pay periods instead of two). Budget off your lowest two-paycheck month, and treat the third paycheck months as bonus cash for your 20% savings bucket. This single habit prevents the most common budgeting failure: assuming every month has identical income when biweekly pay doesn’t work that way.
The 50/30/20 Budget Breakdown for $33k: The Numbers
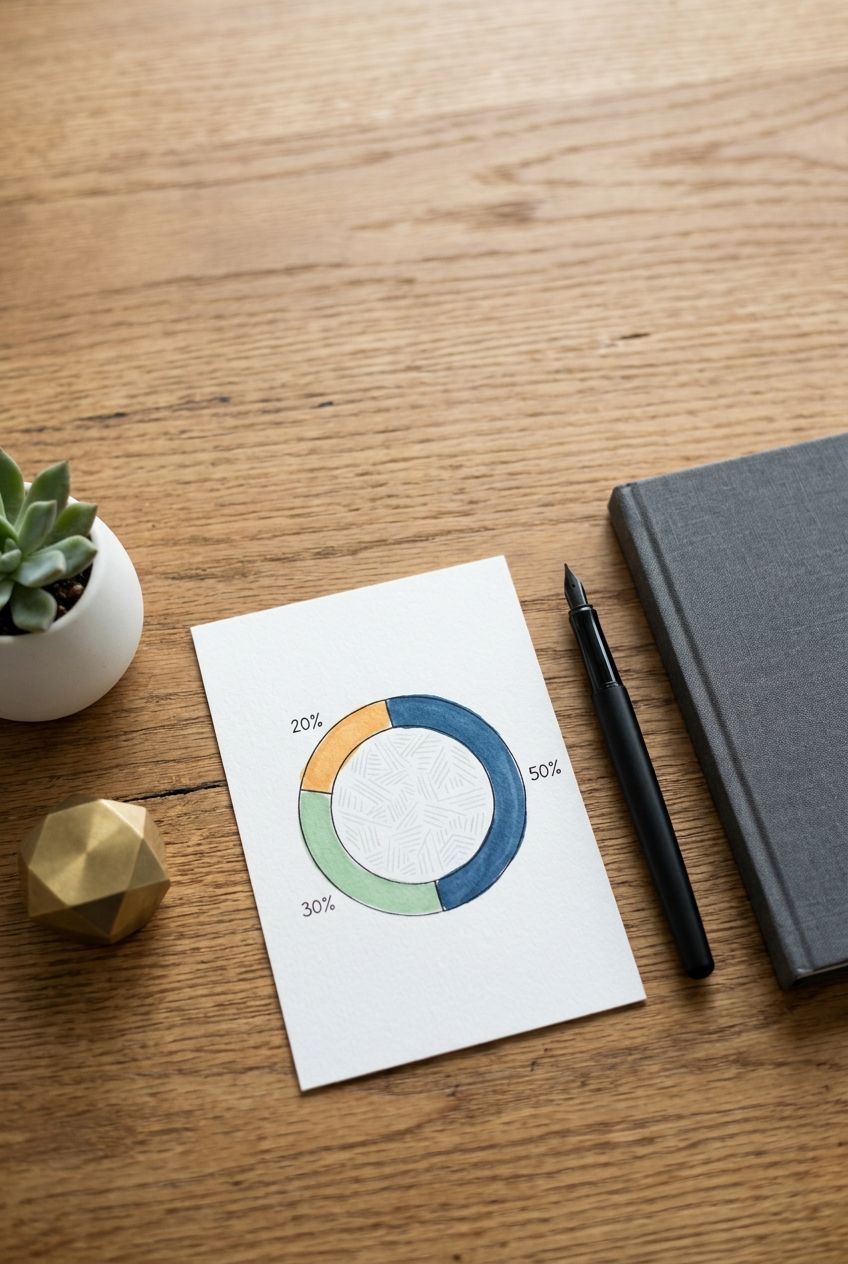
Once you know your net income, the 50/30/20 budget breakdown for a $33k salary is simple math. Using $2,300/month net income:
- 50% Needs: $1,150/month
- 30% Wants: $690/month
- 20% Savings & Debt Payoff: $460/month
That’s the entire framework. The hard part isn’t the math — it’s fitting rent, groceries, transportation, and insurance into $1,150 a month, which in most U.S. cities requires either a roommate, a lower-cost area, or a genuinely lean lifestyle. We’ll cover exactly how to make that work in the next sections.
Needs (50%): What’s Included and What It Really Costs
‘Needs’ means the expenses you cannot skip without real consequences: housing, utilities, groceries, minimum debt payments, insurance, and basic transportation. On $1,150/month, here’s a realistic allocation:
- Rent (including utilities where possible): $650 — this typically requires a studio in a low-cost metro, a room in a shared house, or a small apartment in a rural or mid-size city
- Utilities (electric, gas, water, internet): $120
- Groceries: $250 (roughly $58/week, doable with meal planning and store-brand staples)
- Transportation: $100 (public transit pass, or gas + minimal insurance if you already own a car outright)
- Minimum debt payments (student loans, credit card minimums): $30
Total: $1,150. Notice that health insurance isn’t listed separately — for many $33k earners, this comes through an employer plan pre-tax, which is why we calculated net pay after typical withholdings. If you’re paying for a marketplace plan out of pocket, it needs its own line item here, and something else in this list has to shrink.
The uncomfortable truth: in cities like Boston, San Francisco, or Seattle, $650 doesn’t rent a room, let alone an apartment. That’s addressed later in the high-cost-of-living section — but for a huge portion of the U.S., particularly the Midwest, South, and smaller metros, this breakdown is achievable with a roommate or a modest one-bedroom.
Wants (30%): Spending Without Guilt on $690
The 30% ‘wants’ category is where budgets fall apart — either because people cut it to zero and burn out within six weeks, or they let it swallow the needs and savings categories. On a $33k salary, $690/month for wants is genuinely livable if you prioritize:
- Dining out / takeout: $150 (roughly 2–3 meals out per week at $15–20 each)
- Shopping (clothes, personal items, gifts): $150
- Entertainment & subscriptions (streaming, gym, hobbies): $130
- Travel/fun fund (sinking fund for trips, concerts, events): $200
- Miscellaneous buffer: $60
Total: $690. The travel/fun fund line matters more than people expect — instead of blowing $690 every single month, stash $200 of it into a separate savings account labeled ‘Fun.’ After six months you’ll have $1,200 for a real vacation or a big purchase without touching your emergency fund or going into debt for it.
Savings & Debt Payoff (20%): Building Wealth on $460 a Month
This is the category that determines whether $33k is a dead end or a starting point. $460/month sounds small, but compounded over years, it’s the difference between retiring comfortably and working into your 70s.
Splitting the 20% Bucket
- Emergency fund: $200/month until you hit 3–6 months of expenses (roughly $3,450–$6,900 based on this budget)
- Retirement (401k match first, then Roth IRA): $150/month
- Extra debt payoff (beyond minimums): $110/month
Why the Order Matters
If your employer offers a 401k match, get that match before anything else — it’s a guaranteed 50-100% return that no other line item in this budget can compete with. If there’s no match, prioritize a starter emergency fund of $1,000 first, then split the rest between high-interest debt (anything above 7% APR) and a Roth IRA, which at $33k income you likely qualify for with zero phase-out restrictions.
At $460/month, you’ll hit a fully funded 3-month emergency fund (around $3,450) in roughly 17 months if you dedicate the full $200/month emergency line to it, faster if you temporarily redirect the debt payoff portion once minimum debts are cleared.
50/30/20 Across Different Salaries: A Comparison Table
Seeing the $33k numbers next to other common salary levels shows how the same framework scales — and why the needs category gets proportionally tighter at lower incomes.
| Net Monthly Income | 50% Needs | 30% Wants | 20% Savings/Debt |
|---|---|---|---|
| $2,300 ($33k salary) | $1,150 | $690 | $460 |
| $3,000 ($45k salary) | $1,500 | $900 | $600 |
| $3,850 ($60k salary) | $1,925 | $1,155 | $770 |
| $5,400 ($85k salary) | $2,700 | $1,620 | $1,080 |
Notice that as income rises, the dollar amount available for needs grows quickly, while realistically your actual rent or grocery bill doesn’t scale at the same rate — which is exactly why higher earners can often push savings past 20%, while $33k earners frequently need to push needs past 50% just to cover baseline costs.
Common Mistakes with the 50/30/20 Budget Breakdown at $33k
Most people don’t fail at this framework because the math is hard — they fail because of a handful of predictable errors.
- Budgeting off gross income instead of net. If you calculate 50/30/20 off $2,750 (gross) instead of $2,300 (net), you’ll overallocate by $450/month and wonder why your bank account never matches your spreadsheet. Always start from take-home pay.
- Misclassifying wants as needs. Streaming subscriptions, a car payment on a vehicle nicer than you need, or daily coffee runs are wants, not needs. Be honest here — this is the #1 reason people think 50/30/20 ‘doesn’t work’ for lower incomes when really their needs category is bloated with lifestyle spending.
- Ignoring irregular expenses. Car registration, annual insurance premiums, holiday gifts, and once-a-year subscriptions don’t show up monthly, so people forget to budget for them — then get blindsided in December or during renewal season. Divide annual costs by 12 and build them into your needs or wants category as a monthly line item from day one.
- Treating the 20% as ‘leftover’ instead of a fixed transfer. If savings only happens with whatever’s left at month’s end, it rarely happens. Set up an automatic transfer of $460 to a separate account the day you get paid, before you see the money in your checking account.
- Not adjusting after a raise. When income jumps from $33k to $38k, lifestyle creep quietly eats the increase. Recalculate your 50/30/20 numbers every time your income changes and default any raise toward the 20% bucket first.
What If You Live in a High-Cost-of-Living City?
This is the most common objection to the 50/30/20 budget breakdown at a $33k income level, and it’s a fair one. If your rent alone is $1,200/month in a city like Denver, Austin, or Chicago, the standard 50% needs allocation of $1,150 simply doesn’t cover it. Here’s how to handle it:
- Get a roommate or move slightly outside city center. Even a 15–20 minute commute difference can cut rent by $300–500/month.
- Flip to a 60/20/20 or 65/15/20 split. Instead of forcing an unrealistic 50% needs cap, allow needs to run 60–65% and shrink wants accordingly, while protecting the 20% savings rate as non-negotiable.
- Add a second income stream. Even $200–300/month from freelance work, weekend gig work, or overtime effectively raises your net income and restores breathing room to the original ratios.
- Consider housing subsidies or income-based options. If you qualify, income-restricted housing or a longer commute from a lower-cost suburb can make a meaningful dent.
The framework isn’t broken in expensive cities — the ratios just need honest adjustment. Protecting the 20% savings rate matters more than hitting the exact 50/30 split.
What If You Have Student Loans or Credit Card Debt?
A common scenario: $33k salary, $400/month in student loan payments, and $200/month minimum on a credit card. That’s $600/month already committed — more than half of the entire 50% needs category before rent or groceries.
Here’s the practical fix: treat minimum debt payments as a ‘need’ (they’re not optional), but treat extra debt paydown as a shared priority with the 20% category. Restructure the budget like this:
- Needs (including minimum debt payments): 55–60% instead of 50%
- Wants: reduce to 15–20% temporarily
- Extra debt payoff + minimal savings: keep at 20%, prioritizing a $1,000 starter emergency fund before aggressive extra payments
Once high-interest debt (above 7-8% APR) is cleared, wants can climb back toward the standard 30% and the freed-up cash flow accelerates your actual savings rate well past 20%.
Adjusting the Ratios: When 50/30/20 Doesn’t Fit Your Life
The 50/30/20 rule is a starting template, not a law. On $33k specifically, three common variations work better for real households:
The 60/20/20 Variation
Best for high-cost areas or single-income households. Needs get 60% ($1,380), wants drop to 20% ($460), savings stays protected at 20% ($460). This keeps your savings rate intact even when housing costs are unavoidably high.
The 55/25/20 Variation
A middle-ground option for people with moderate debt or slightly above-average rent. Needs get 55% ($1,265), wants drop to 25% ($575), savings stays at 20% ($460).
The 50/20/30 Variation
Best for aggressive debt payoff or early retirement goals. Needs stay at 50% ($1,150), wants shrink to 20% ($460), and savings/debt payoff jumps to 30% ($690) — ideal once you’ve eliminated high-interest debt and want to accelerate an emergency fund or retirement contributions.
Whichever variation you choose, keep the core discipline: separate accounts for each category, automated transfers on payday, and a monthly 15-minute review to catch categories that are drifting.
Tools That Make This Breakdown Easier to Track
Manually tracking three categories across a $2,300 monthly budget is doable with a spreadsheet, but a few tools remove the friction entirely:
- YNAB (You Need A Budget): $14.99/month or $109/year, built specifically around zero-based budgeting that pairs well with the 50/30/20 structure
- EveryDollar: free tier covers manual budget tracking, ideal for a $33k salary where every category needs to be watched closely
- A simple three-account system: one checking account for needs, one for wants, and one high-yield savings account for the 20% bucket — no app required, just automatic transfers set up through your bank on payday
The three-account method works particularly well at this income level because it makes overspending in the wants category physically impossible once the money’s gone — there’s no dipping into needs funds by accident.
Making the 50/30/20 Budget Breakdown Work Long-Term on $33k
The numbers in this guide aren’t meant to be followed to the exact dollar forever — they’re a starting framework to build discipline around, then adjust as your rent, debt, and income change. Recalculate this breakdown every time you get a raise, move, or pay off a debt, and default the difference toward your 20% savings bucket before lifestyle creep claims it. Start with automated transfers on payday, track your three categories for 60 days without judgment, then adjust the ratios to fit your real life rather than forcing your real life to fit an internet rule. That’s how a $33k salary turns into a stable financial base instead of a paycheck-to-paycheck cycle.