The 50/30/20 Budget for Teachers: A Step-by-Step Guide That Actually Fits a Teacher’s Paycheck
The average U.S. public school teacher spends roughly $500 of their own money on classroom supplies every year, yet most budgeting advice ignores that line item completely. Generic rules assume a 12-month paycheck, a desk job, and no $60 trip to the craft store. This guide rebuilds the 50/30/20 budget for teachers from the ground up, using real salary figures, real pay schedules, and the quirks of a school-year income.
What the 50/30/20 Budget for Teachers Actually Means (and Why the Standard Version Breaks)
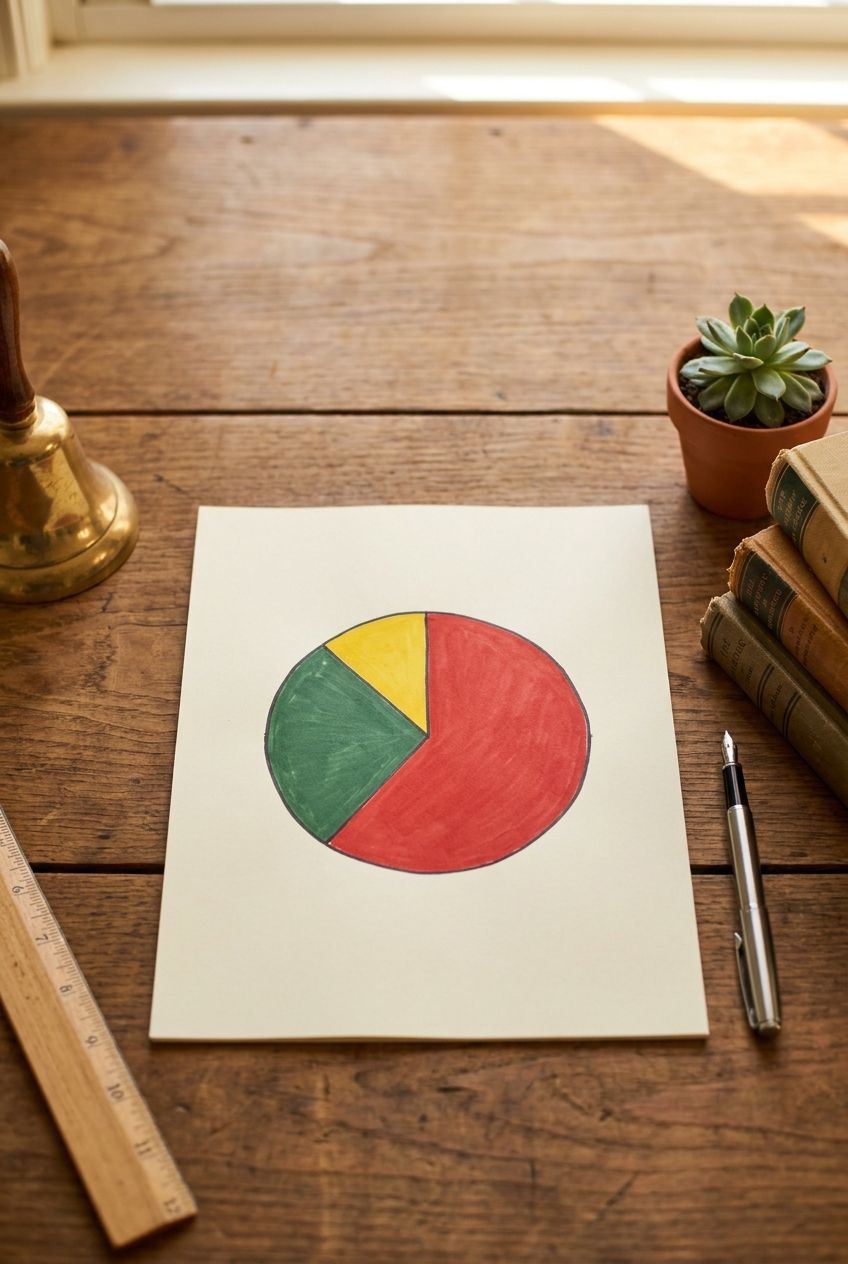
The 50/30/20 rule splits your after-tax income (your take-home pay, the amount that lands in your bank account) into three buckets. Fifty percent goes to needs, 30 percent to wants, and 20 percent to savings and debt repayment. Senator Elizabeth Warren popularized it in her 2005 book All Your Worth, and it has survived because it is simple enough to remember at a grocery store checkout.
Here is what each bucket means in plain terms:
- Needs (50%): expenses you cannot skip without serious consequences, such as rent or mortgage, utilities, groceries, insurance, transportation, and minimum debt payments.
- Wants (30%): everything that improves life but is not essential, like dining out, streaming, hobbies, travel, and gym memberships.
- Savings and debt payoff (20%): emergency fund contributions, retirement savings beyond your pension, and any extra payments on loans.
The standard version breaks for teachers in three places. First, teacher pay is often paid over 10 months instead of 12, so “monthly income” is slippery. Second, pension and health insurance deductions come out before your paycheck arrives, which changes what counts as savings. Third, out-of-pocket classroom spending has no obvious home in any of the three buckets.
The fix is not to abandon the framework. It is to adjust the inputs. The rest of this guide shows exactly how.
How to Calculate Your Real Take-Home Pay in 15 Minutes
Your gross salary is a vanity number for budgeting purposes. The 50/30/20 rule runs on net pay, so start there.
Step-by-step: find your true monthly number
- Pull your last three pay stubs. Log into your district’s payroll portal (many use ADP, Skyward, or Frontline) and download them. Success looks like three PDFs on your screen.
- Write down your net pay per check. This is the deposit amount, after taxes, pension, and benefits. But what if your net pay varies? Average the three stubs, which smooths out odd deductions.
- Multiply by the number of checks per year. Most districts pay 24 times (twice monthly) or 26 times (biweekly). A teacher netting $1,900 per biweekly check takes home $49,400 per year.
- Divide by 12, not 10. This is the step that trips people up. If you are paid over 10 months, divide your annual net by 10 to get your school-year monthly figure, and note it separately.
A worked example
A teacher in Ohio earning $52,000 gross nets about $3,300 per month after federal tax, state tax, the State Teachers Retirement System contribution (14% of gross), and health premiums. That is the number you multiply by 50, 30, and 20 percent.
- Needs (50%): $1,650
- Wants (30%): $990
- Savings and debt (20%): $660
One caveat: if your pension is mandatory, do not count it toward your 20%. It is already gone before you see the money. Treat it as a bonus, not a substitute for personal savings.
The 10-Month vs. 12-Month Pay Problem: How to Budget Through Summer Without Panic
If you are paid over 12 months, your checks are smaller but steady. If you are paid over 10 months, your checks are larger but stop in June. Both work with the 50/30/20 budget for teachers, but they require different setups.
If you get paid over 12 months
Budget exactly as described above. Your monthly net is consistent, so apply the percentages directly. The only risk is the first summer, when the lack of a school-year routine tempts you to overspend your wants category.
If you get paid over 10 months
You need a summer bridge fund, which is a dedicated savings account that covers June through August bills. Here is how to build one:
- Add up your fixed needs for one month (rent, utilities, insurance, minimum debt payments). Say it comes to $2,100.
- Multiply by 2 or 3 months of summer coverage: $4,200 to $6,300.
- Divide by 10 school-year months: $420 to $630 per month goes into a separate high-yield savings account, such as Ally, Marcus by Goldman Sachs, or Capital One 360, all paying roughly 4% APY at the time of writing.
- Count that monthly transfer as part of your 20% savings bucket.
What if you cannot afford $500 a month for this? Ask your district’s HR office whether you can switch to 12-month pay. Many districts allow this election once a year, usually in spring. It costs you nothing and removes the bridge problem entirely.
Success looks like this: on July 1, your bridge account shows enough to cover two full months of needs without touching your emergency fund.
Sorting Your Needs: Where Teacher-Specific Expenses Land in the 50%
The 50% bucket is where most teachers feel the squeeze, especially in high-cost metros. If your needs exceed 50%, you are not failing. You are in the majority. The median U.S. renter spends about 30% of gross income on housing alone, and teacher salaries start near $44,000 in many states.
What belongs in your needs bucket
- Housing: rent or mortgage, plus renters or homeowners insurance.
- Utilities: electric, water, gas, and one internet plan. A 100 Mbps plan runs $40 to $60 per month.
- Groceries: the USDA’s moderate-cost plan estimates roughly $300 to $400 per month for a single adult.
- Transportation: car payment, insurance, gas, or a transit pass.
- Health costs: premiums not already deducted, prescriptions, copays.
- Minimum debt payments: student loans, credit cards, car loans.
- Required professional costs: certification renewals, mandatory continuing education, and union dues if not deducted.
The classroom supply question
Is spending $400 a year on classroom supplies a need or a want? Be honest: if your school provides no supply budget and you cannot teach without the item, it is a need. If you are buying a $45 set of themed bulletin board borders, it is a want. Set a fixed annual classroom budget (for example, $360, or $30 per month) and keep a separate sinking fund for it.
You can also claim up to $300 of unreimbursed classroom expenses on your federal tax return through the Educator Expense Deduction, so save every receipt. Photograph them with your phone the day you buy.
Student Loans and the 20% Bucket: Pay Down, Forgive, or Both?
The average teacher with student debt owes somewhere between $30,000 and $60,000, depending on whether they hold a master’s degree. How you handle this decides whether your 20% bucket builds wealth or just treads water.
Check forgiveness before you pay extra
Before sending one extra dollar to your loans, find out whether you qualify for forgiveness. Two programs matter most:
- Public Service Loan Forgiveness (PSLF): forgives the remaining balance after 120 qualifying payments (10 years) while working full time for a public school or nonprofit. You must be on an income-driven repayment plan, and you need to submit the employer certification form annually.
- Teacher Loan Forgiveness: forgives up to $5,000, or up to $17,500 for math, science, or special education teachers, after five consecutive years at a low-income school.
But what if you pay extra and then qualify for forgiveness? You would have wasted money. If you are on track for PSLF, pay the required minimum, count it as a need, and direct your entire 20% toward emergency savings and retirement instead.
When aggressive payoff makes sense
If you work at a private school that does not qualify for PSLF, or you hold high-interest private loans above 7%, pay them off aggressively. The 20% bucket should attack the highest-rate debt first, a method called the avalanche approach. Success looks like a loan balance that drops by more than your monthly interest charge.
Retirement Savings: How 403(b), 457(b), and Your Pension Fit the 20%
Teachers get retirement options that most workers envy, but the alphabet soup confuses people. Here is how to sort it out.
A pension (technically a defined benefit plan) promises a set monthly payment in retirement based on your years of service and final salary. You usually do not control it. A 403(b) is a tax-advantaged retirement account for public school and nonprofit employees, similar to a 401(k). A 457(b) is a similar account with the bonus that early withdrawals avoid the usual 10% penalty. In 2024, you could contribute up to $23,000 to a 403(b), plus a $7,500 catch-up if you are over 50.
A practical order of operations for your 20% bucket:
- Build a starter emergency fund of $1,000 first.
- Capture any employer match in your 403(b). Free money beats everything.
- Finish a full emergency fund of three to six months of needs.
- Open a Roth IRA through Fidelity, Schwab, or Vanguard and contribute up to $7,000 per year (2024 limit).
- Return to the 403(b) to raise contributions toward 10 to 15 percent of gross pay.
Watch out for high-fee 403(b) providers. Some district-endorsed plans charge annuity fees of 1.5% to 2.5% per year, which can consume hundreds of thousands of dollars over a career. Compare expense ratios and favor index funds charging under 0.20%.
Comparison: Three Budgeting Frameworks for Teachers (and Which to Choose)
The 50/30/20 rule is not the only option. Here is how it compares with two alternatives that teachers frequently consider.
| Framework | Setup Time | Best For | Weakness |
|---|---|---|---|
| 50/30/20 | 30 to 60 minutes | Teachers new to budgeting who want a simple guardrail | Fails in high-cost cities where needs top 60% |
| Zero-based budgeting (YNAB, EveryDollar) | 2 to 3 hours, then 15 minutes weekly | Teachers with irregular income, debt to crush, or a tendency to overspend | Time-intensive; YNAB costs about $109 per year |
| Pay yourself first (automate savings, spend the rest) | 20 minutes | Teachers who hate tracking receipts and want hands-off progress | No guardrails on spending, so wants can balloon |
The recommendation by use case: choose 50/30/20 if you have never budgeted and want a quick start. Choose zero-based budgeting if you are carrying credit card debt or are paid over 10 months. Choose pay yourself first if you already live below your means and just need to automate. Many teachers start with 50/30/20, then graduate to zero-based after six months of tracking.
The Teacher’s Customized Split: When 50/30/20 Becomes 60/20/20
Here is the honest truth: if you live in San Francisco, Boston, or Seattle on a starting teacher salary near $60,000, your housing alone can swallow 50% of your take-home pay. Insisting on a strict 50/30/20 split in that situation just creates guilt.
Adjusted ratios that work
- 60/20/20: for high-cost cities. Trim wants to 20% and hold the line on savings.
- 55/25/20: for teachers carrying a car payment or childcare costs.
- 50/20/30: for teachers on forgiveness tracks or with high-interest debt to eliminate. Flip wants and savings.
- 70/10/20: a short-term emergency split for a lean season, such as a first year after a move.
The principle is to protect the 20%. When income is tight, squeeze wants before savings, because the savings habit is much harder to rebuild than a streaming subscription.
Using a side income without wrecking the plan
Many teachers tutor ($40 to $80 per hour), coach ($2,000 to $5,000 per season), or sell on Teachers Pay Teachers. Route every dollar of side income through a simple rule: 100% goes into the 20% bucket until your emergency fund is full, then split it 50/50 between savings and wants. Do not fold it into your regular needs budget, or you will build lifestyle costs that vanish when the gig ends.
Three Common Budgeting Mistakes Teachers Make (and How to Fix Each)
Mistake 1: Budgeting from gross salary
A $58,000 salary sounds like $4,833 a month. Your actual deposit might be $3,600. Budgeting from the bigger number produces a plan that is 25% too optimistic and collapses by week three. Fix: always build from the deposit amount on your pay stub.
Mistake 2: Ignoring irregular costs
Car registration, back-to-school supplies, holiday gifts, and professional development fees arrive once or twice a year, so they ambush monthly budgets. Fix: create sinking funds, which are small monthly contributions toward a known future expense. If you spend $600 each August on classroom setup, save $50 per month. Open free sub-accounts in Ally or Capital One 360 and name them.
Mistake 3: Letting the summer erase your progress
Teachers on 10-month pay often cruise through the school year, then burn through savings in July. Fix: write a summer spending cap before June. For example, allocate $1,200 for the full summer wants budget and move it to a separate checking account so it is visible and finite.
Mistake 4: Never reviewing the plan
A raise, a new baby, or a move changes everything. Fix: set a recurring calendar reminder for the first Sunday of each quarter and spend 20 minutes comparing planned versus actual spending.
“But What If…?” Answering the Objections Teachers Raise Most Often
“What if my salary is too low for 50/30/20 to work?” Then start with 5% savings and build up one percentage point each quarter. A teacher who saves 5% now and raises it by 1% every three months reaches 20% in four years. Progress beats perfection.
“What if I support family members or have kids?” Childcare often costs $800 to $1,500 per month and belongs in needs. Use the 55/25/20 or 60/20/20 split and lean on dependent care FSAs, which let you set aside up to $5,000 of pre-tax dollars for childcare.
“What if I am a first-year teacher with a $1,000 monthly deficit?” Check whether your district offers signing bonuses, housing stipends, or first-year mentoring pay. Consider a summer job. Cut the three biggest needs categories first, usually housing (get a roommate), transportation (carpool), and groceries (meal-prep on Sundays).
“What if I hate tracking every purchase?” You do not need to. Automate the 20% on payday, pay fixed bills by autopay, and keep the remaining 30% in a single debit-card checking account. When that account hits zero, wants are done for the month. No receipts required.
“What if my spouse earns a different amount?” Calculate the 50/30/20 on combined take-home pay, then each partner contributes proportionally to income. Keep a small personal wants allowance for each person, such as $100 to $200, to prevent budget arguments.
Set Up Your 50/30/20 Budget for Teachers in 60 Minutes
Do not wait for January 1 or the first day of school. Use this timed plan to finish in one sitting.
- Minutes 0 to 10: Gather data. Download three pay stubs and your last two bank statements.
- Minutes 10 to 20: Calculate net monthly income. Use the formula from earlier. Write the number at the top of a blank page.
- Minutes 20 to 35: Categorize last month’s spending. Highlight every transaction in one of three colors: needs, wants, savings. Use a free tool like Google Sheets or the Monarch Money trial.
- Minutes 35 to 45: Compare against 50/30/20. Note where you are over or under. Choose your adjusted ratio if needed.
- Minutes 45 to 55: Automate. Set up a recurring transfer to savings on the day after payday. Schedule bill autopays. Open sinking fund sub-accounts.
- Minutes 55 to 60: Set a review date. Put a 20-minute check-in on your calendar 30 days out.
Your next action is concrete: open your payroll portal right now, pull your latest pay stub, and write down your net monthly pay. That single number is the foundation of everything above, and it takes under five minutes to find.