The 50/30/20 Budget for a $22k Salary: A Realistic Framework Guide
A $22,000 salary works out to about $1,833 a month before taxes — and if you’ve ever tried to stretch that across rent, groceries, and gas, you already know that the textbook advice to ‘save 20%’ can feel disconnected from reality. But the 50/30/20 budget for a $22k salary can still work; it just needs to be built around your actual take-home pay, not a generic percentage pulled from a personal finance book written for someone earning double what you make.
This guide walks through the real math, realistic category breakdowns, and the adjustments you’ll likely need to make when your income sits well below the national median. No fluff — just numbers you can use today.
What the 50/30/20 Budget for a $22k Salary Actually Looks Like
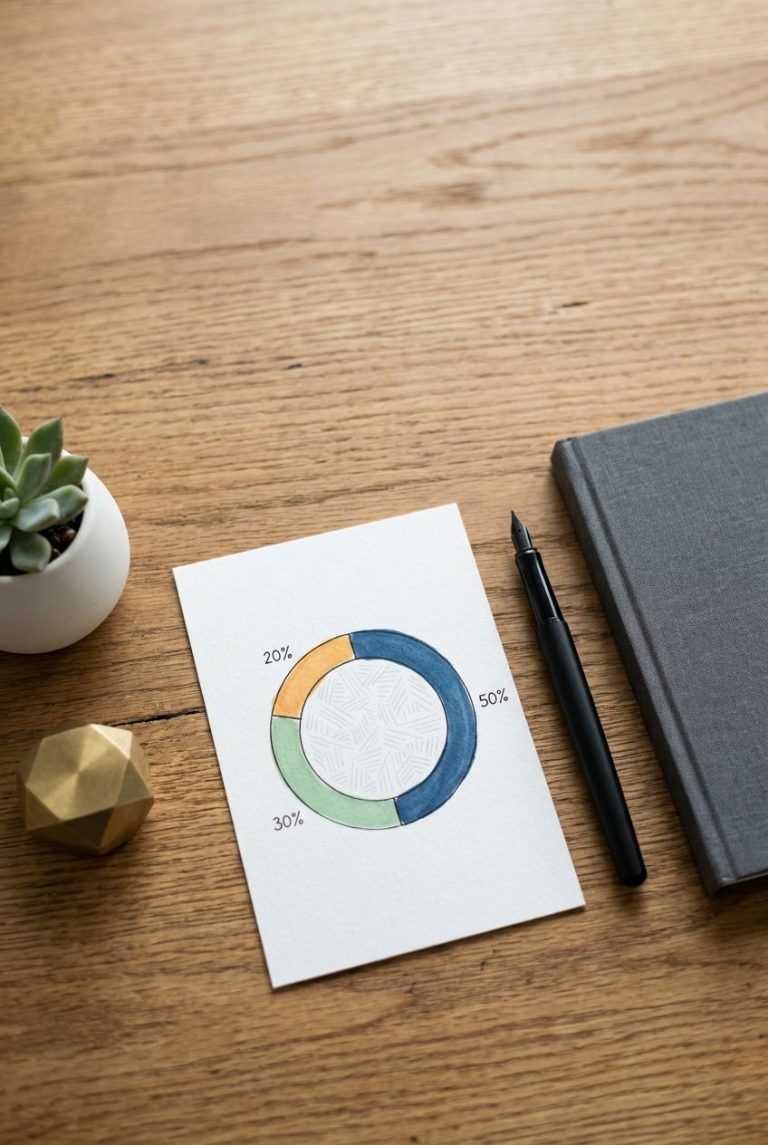
The 50/30/20 rule, popularized by Senator Elizabeth Warren in her book ‘All Your Worth,’ splits your after-tax income into three buckets: 50% for needs (housing, food, transportation, utilities, minimum debt payments), 30% for wants (dining out, entertainment, subscriptions), and 20% for savings and extra debt payoff.
The mistake most people make right away is applying these percentages to their $22,000 gross salary instead of their net pay. Nobody’s paycheck hands them $1,833 a month in full — taxes and deductions come out first. On a $22k salary for a single filer with no dependents, take-home pay typically lands somewhere between $1,600 and $1,700 per month, depending on your state and withholding elections.
For this guide, we’ll use a working figure of $1,650 net monthly income, which produces these targets:
- Needs (50%): $825/month
- Wants (30%): $495/month
- Savings/Debt (20%): $330/month
These numbers are your starting point, not gospel. In several sections below, you’ll see why many people earning $22k need to shift toward a 60/30/10 or even 70/20/10 split, at least temporarily.
Step 1: Find Your Real Take-Home Pay (Not Your Gross Salary)
Before you assign a single dollar, calculate what actually hits your bank account. Skipping this step is the single most common reason 50/30/20 budgets fail in the first month.
Federal Taxes and FICA on a $22,000 Income
Using 2024 tax brackets for a single filer with the standard deduction of $14,600, your taxable income drops to $7,400. That puts you entirely in the 10% federal bracket, meaning roughly $740 in federal income tax for the year, or about $61.67/month.
FICA taxes (Social Security + Medicare) are a flat 7.65% of gross wages with no deductions applied — that’s $1,683/year, or $140.25/month. Combined, federal tax and FICA remove about $201.92/month from your paycheck.
State Taxes and Other Deductions
If you live in a state with no income tax — Texas, Florida, Tennessee, Nevada, Washington, Wyoming, South Dakota, or Alaska — your take-home pay stays closer to $1,631/month. If you live in a state with income tax, such as California or New York, expect another $20–$60/month withheld depending on credits for low-income earners (many states offer earned income credits that reduce this significantly).
If your employer offers health insurance and you’re enrolled, subtract that premium too — even a modest $50/month plan changes your real number. Pull up your last two pay stubs and average them; that’s your true monthly income to budget against, not a calculator estimate.
The 50% Needs Category: Housing, Food, and Transportation on $825/Month
This is where the 50/30/20 budget for a $22k salary gets genuinely difficult, because $825/month for all essential expenses is tight in most U.S. markets. Here’s how it typically has to be split.
Housing Reality Check
The average one-bedroom apartment in the U.S. rents for around $1,400–$1,600/month as of 2024 — already blowing past the entire needs category. To make 50/30/20 work at this income, housing usually has to come from one of these paths:
- Renting a room in a shared house ($450–$650/month in most mid-sized cities)
- Living with family or a partner and splitting costs
- Subsidized or income-based housing (Section 8, where rent is capped at 30% of income)
- Rural or low-cost-of-living areas where studio apartments run $600–$750/month
Budget target: $550–$600/month for rent + utilities combined.
Groceries and Food Costs
Using the USDA’s ‘Thrifty Food Plan’ as a benchmark, a single adult can eat on roughly $220–$260/month buying groceries strategically — think Aldi, generic brands, bulk rice/beans/pasta, and minimal pre-packaged food. Target: $150–$175/month if you’re also allocating some food money from the wants category for dining out.
Transportation
A paid-off older car with liability-only insurance (around $50–$70/month) plus $80–$100 in gas is common. If you live somewhere with reliable public transit, a monthly pass ($60–$100 in most cities) is often cheaper than car ownership. Target: $75–$100/month.
The 30% Wants Category: What $495/Month Actually Buys You
Wants aren’t optional fluff to eliminate entirely — they’re what keep a budget sustainable long-term. Here’s a realistic split of a $495/month wants budget:
- Dining out / takeout: $100 (about 3-4 modest meals out per month)
- Entertainment (streaming, movies, events): $60
- Personal care (haircuts, toiletries, clothing): $120
- Subscriptions (Netflix, Spotify, gym): $35
- Miscellaneous / fun money: $180
That last category matters more than people think — having even $150–$180 with zero justification required prevents the burnout that causes people to abandon budgeting entirely after six weeks.
The 20% Savings and Debt Bucket: Building a Safety Net on $330/Month
Emergency Fund Priority
If you have less than $500 in savings, put the majority of this bucket — say $200/month — toward a starter emergency fund until you hit $1,000. At $200/month, that takes five months. After that, redirect toward a 3-month expense cushion, which at $825/month in needs means a $2,475 target.
Retirement Contributions
Even on $22k, a Roth IRA is worth prioritizing because your low tax bracket means you’re contributing after-tax dollars you’re barely taxed on anyway. Contributing $50–$100/month ($600–$1,200/year) into a Roth IRA through Fidelity or Schwab (both offer $0 minimums) builds a habit that compounds significantly over 30+ years.
Debt Payoff Strategy
If you’re carrying credit card debt, use the avalanche method (highest interest rate first) or the snowball method (smallest balance first) with whatever remains of your 20% bucket. Even an extra $80/month above minimums on a $1,500 balance at 22% APR cuts your payoff time by more than a year compared to minimum payments alone.
50/30/20 vs. Other Budget Splits for Low-Income Earners
The standard 50/30/20 split assumes housing costs that consume half your income are manageable — which isn’t always true below $25k/year. Here’s how it compares to alternative frameworks:
| Framework | Needs | Wants | Savings/Debt | Best For |
|---|---|---|---|---|
| 50/30/20 | 50% | 30% | 20% | Low-cost housing markets, roommates, or subsidized rent |
| 60/30/10 | 60% | 30% | 10% | High-rent areas where housing alone exceeds 40% of income |
| 70/20/10 | 70% | 20% | 10% | Supporting dependents or carrying high fixed debt payments |
| 80/10/10 | 80% | 10% | 10% | Temporary crisis mode — job loss, medical bills, relocation |
If your rent alone eats 45% of your take-home pay, don’t force a 50/30/20 split and call yourself a budgeting failure — shift to 60/30/10 until your income rises or your housing cost drops, then transition back.
Common Mistakes When Applying 50/30/20 to a $22k Salary
These three mistakes account for most of the frustration people report when trying this framework on a lower income:
- Budgeting off gross pay instead of net pay. This alone creates a $150–$200/month gap that makes every category feel impossible to hit. Always start from your actual bank deposit.
- Treating the 20% savings target as non-negotiable from month one. If you have zero emergency fund and $3,000 in high-interest debt, forcing a rigid 20% before stabilizing your needs category often backfires — you end up dipping into savings within weeks. Build a $500 buffer first, even if it means temporarily running 55/30/15.
- Ignoring irregular expenses. Car registration, annual subscriptions, holiday gifts, and unexpected medical copays don’t show up in a basic monthly budget but absolutely will occur. Set aside $20–$30/month in a separate ‘irregular expenses’ sinking fund pulled from the needs category to avoid blowing your budget every few months.
What If $22k Isn’t Enough to Cover the 50% Needs Category?
This is the most common objection, and it’s a fair one. If your rent alone is $900/month, no percentage-based rule fixes that math. Here’s how to handle it realistically:
If housing exceeds 45% of your take-home pay: Look at a roommate situation, a housing subsidy program (contact your local Public Housing Authority about Section 8 waitlists), or relocating to a lower cost-of-living area. A move from a city averaging $1,500/month rent to a smaller town averaging $700/month is often the single biggest budget fix available.
If you’re supporting dependents: The 50/30/20 framework wasn’t designed with childcare or dependent support in mind. Shift to 65/25/10 and prioritize the SNAP (food assistance) and childcare subsidy programs many states offer to households near this income level — eligibility often extends up to 130-185% of the federal poverty line, which a $22k salary frequently falls within.
If you can’t hit even 10% savings some months: That’s fine short-term. Track it, don’t ignore it, and aim to average 10% over a quarter rather than hitting it every single month. Consistency over a 3-month window matters more than perfection in any single 30-day period.
Practical Ways to Stretch a $22k Budget Further
Beyond restructuring percentages, these concrete moves free up real cash:
- Claim the Earned Income Tax Credit (EITC). A single filer earning $22k with no children can qualify for up to $632 back at tax time (2024 figures) — file even if you think you don’t need to.
- Apply for SNAP benefits. Single-person households earning under roughly $1,632/month gross often qualify, which can free up $150–$250/month previously spent on groceries.
- Negotiate or shop your car insurance annually. Switching providers can save $20–$40/month for identical coverage — use a comparison tool like The Zebra or Policygenius once a year.
- Use a no-fee checking account with cashback or interest. SoFi and Chime both offer accounts with no minimum balance and small interest yields (around 2%) that add up over a year.
- Pick up 5-8 hours/week of gig work. Even at $15/hour, that’s an extra $300–$480/month — enough to fully fund the savings category on its own.
Sample Monthly Budget Breakdown for a $22k Salary
Putting it all together, here’s what a full month looks like using the $1,650 net income figure:
| Category | Line Item | Amount |
|---|---|---|
| Needs | Rent + utilities (shared housing) | $575 |
| Needs | Groceries | $150 |
| Needs | Transportation (insurance + gas) | $80 |
| Needs | Phone plan | $20 |
| Wants | Dining out | $100 |
| Wants | Entertainment/subscriptions | $95 |
| Wants | Personal care | $120 |
| Wants | Miscellaneous/fun money | $180 |
| Savings/Debt | Emergency fund | $180 |
| Savings/Debt | Roth IRA | $75 |
| Savings/Debt | Extra debt payment | $75 |
Total: $1,650 — fully allocated, with room to adjust as your rent, location, or dependents change the math.
Making the 50/30/20 Budget Stick Long-Term
A budget built on paper means nothing if it collapses by week three. Track every transaction for the first 30 days using a free tool like Mint, EveryDollar, or even a simple notes app — the goal isn’t perfection, it’s finding out where your actual spending diverges from your plan. Most people discover their ‘wants’ category is underestimated by $50–$100 the first time they track honestly.
Revisit your percentages every 90 days, especially if you get a raise, move, or pick up extra income. A budget built for $22k should evolve the moment your income does — treat it as a living document, not a one-time exercise.
Conclusion: Start With Your Real Numbers, Not the Ideal Ones
The 50/30/20 budget for a $22k salary isn’t a rigid formula — it’s a starting framework you bend until it fits your actual rent, actual grocery bill, and actual paycheck. If the math doesn’t work at 50/30/20, run 60/30/10 without guilt, fix your emergency fund before your Roth IRA if you have to, and revisit the split every time your income or expenses shift. The goal isn’t a perfect spreadsheet; it’s a plan you can actually follow next month, and the month after that.